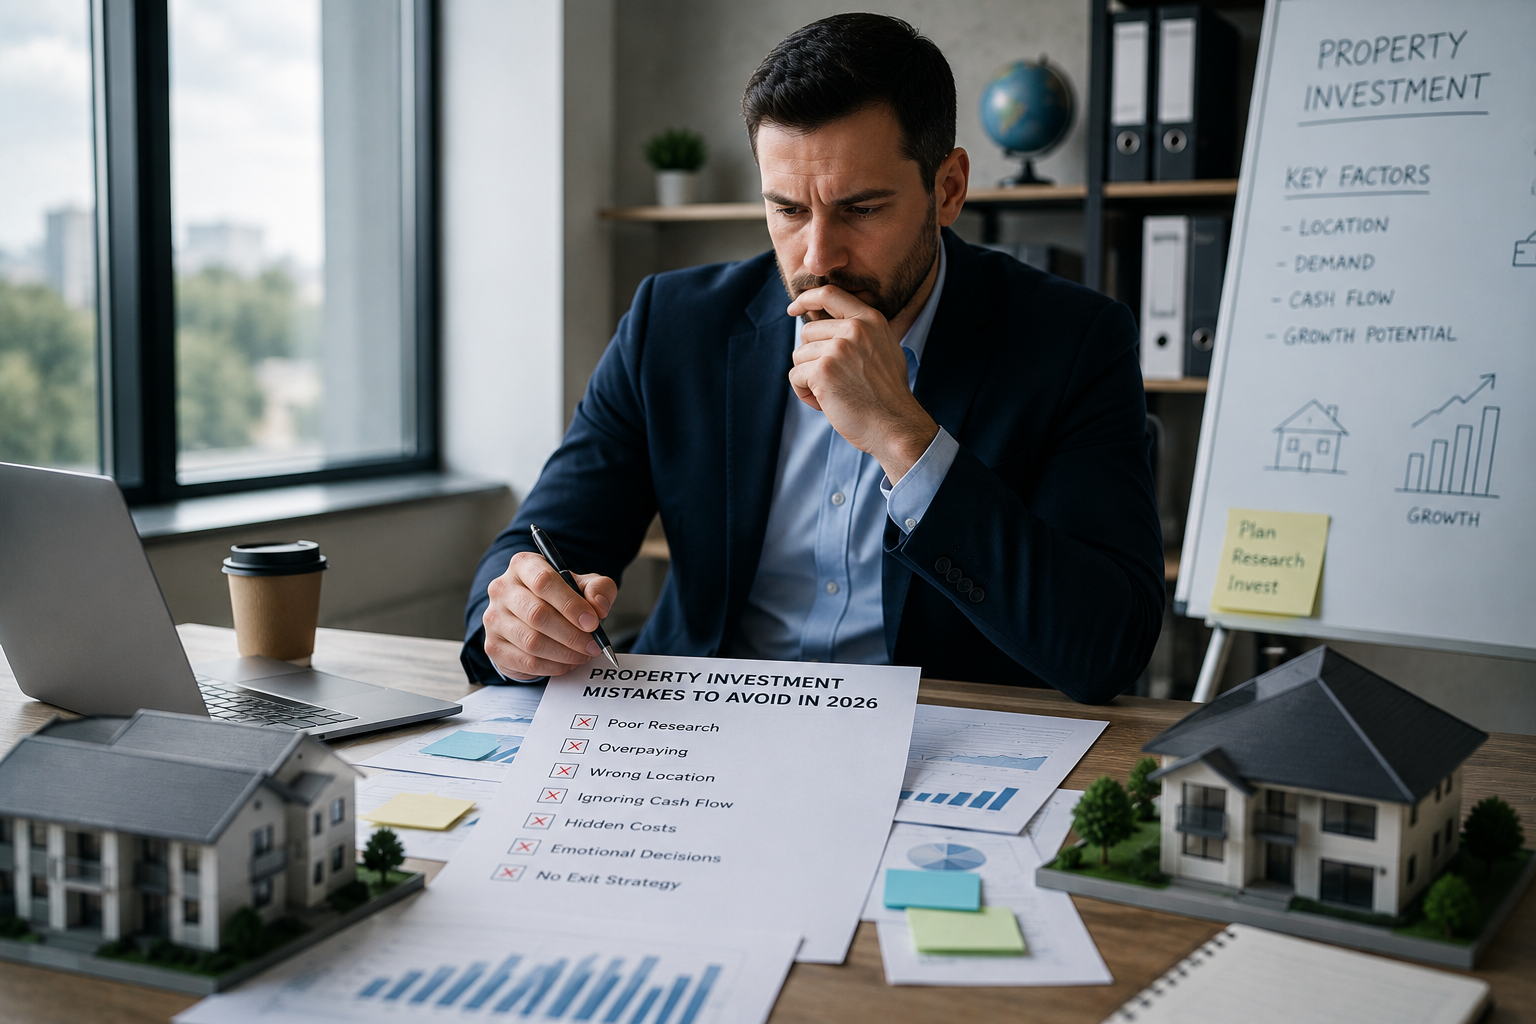
A poor investment decision does not always look reckless. It may be a new apartment with an impressive brochure, a cheap house in a town receiving media attention, or a property recommended because “land always goes up”. The problem is not the slogan. The problem is buying without testing whether the asset fits your goals, finances and next purchase.
Australia is not one property market. Melbourne, regional Victoria and interstate markets can move differently, and two properties in the same postcode can deliver very different results. Avoiding mistakes therefore requires a process, not a prediction.
Opening property portals feels productive, but it can lead you towards whatever looks attractive rather than what your portfolio needs. A clear property investment strategy should define your objective, budget, preferred balance of capital growth and cash flow, acceptable risk, holding period and likely next step.
For example, an investor planning to buy again within three years may need a different asset and cash buffer from someone purchasing one property for retirement income. The first question should not be “Which suburb is hot?” It should be “What job must this property do?”
A lender may approve a certain amount, but approval does not automatically mean the repayments and ownership costs will feel comfortable. Borrowing to invest magnifies gains and losses. Interest costs continue even when a property is vacant or needs repairs.
Build your budget around several scenarios:
A cash buffer is not idle money. It protects the investment plan from becoming a forced sale.
The purchase price is only the first number. Depending on the property and location, investors may also need to allow for stamp duty, conveyancing, inspections, loan costs, insurance, council and water rates, owners corporation fees, land tax, property management, maintenance and compliance work.
Tax outcomes also vary by ownership structure and personal circumstances. Keep clean records from the beginning and obtain advice from a qualified accountant or tax adviser. A tax deduction can reduce a cost, but it does not turn a weak property into a strong investment.
Population growth is useful, but it is not enough on its own. Investors should ask where new residents work, what they can afford, what housing they prefer and how much competing supply is planned.
Good property research and acquisition examines several connected indicators, including employment diversity, household income, vacancy rates, days on market, rental affordability, infrastructure, building approvals and the local supply pipeline.
A fast-growing outer area may still struggle if large volumes of similar land and housing can be released. A mature suburb with slower population growth may have stronger scarcity, established amenities and broader owner-occupier demand. Context matters more than a single ranking.
A low purchase price can reduce the entry cost, but it does not guarantee value. A cheap property may have limited tenant demand, high maintenance, weak resale appeal or few future buyers.
Ask practical questions. Who will rent the property? Why would they choose it over nearby alternatives? Who is likely to buy it from you later? Is the layout useful? Does the street appeal to owner-occupiers? Is there natural light, parking, storage and usable outdoor space?
The strongest asset is often not the cheapest one. It is the property that remains useful and appealing through different market conditions.
Land can support long-term scarcity and flexibility, but raw square metres do not tell the whole story. Irregular shape, steep slope, easements, vegetation controls, flood or bushfire overlays, heritage restrictions and poor vehicle access can reduce what is realistically possible.
Before paying a premium, investigate the planning zone, overlays, frontage, services, site constraints and likely buildable area. Our guide to why land size matters for long-term property growth explains how to judge land quality, not just land quantity.
New property can offer lower initial maintenance and depreciation benefits, but it may also carry a developer margin, a price premium and significant competing supply. In apartment markets, many near-identical properties can be listed for rent or sale at once.
Review the developer and builder, contract, owners corporation forecast, comparable established sales and future projects nearby. The key question is whether the property is scarce and well priced, not simply whether it is new.
Strong suburb data cannot compensate for serious defects or an unfavourable contract. Arrange appropriate building and pest inspections, review the contract with a conveyancer or solicitor and examine relevant council, title and owners corporation information.
Due diligence should consider:
Optimistic rent and maintenance assumptions can make almost any property look affordable. Use a conservative rent supported by local evidence, allow for vacancy and management, and separate regular costs from irregular capital expenses.
Also distinguish gross yield from net cash flow. Gross yield ignores many ownership and finance costs. A property with an attractive headline yield may leave less money in your pocket after all expenses are included.
Owning properties in different suburbs does not automatically create diversification. If each property depends on the same employer, tenant group, property type or economic driver, the portfolio may still be concentrated.
Portfolio decisions should consider location, price point, tenant market, dwelling type, debt exposure and cash-flow profile. This becomes increasingly important when you build a property portfolio step by step.
If one answer is unclear, pause and investigate. Missing a property is usually less costly than buying the wrong one.
Avoiding property investment mistakes in 2026 is not about waiting for certainty. It is about replacing assumptions with evidence. Start with a defined strategy, use conservative numbers, investigate the local supply and demand story, assess the individual asset and protect your cash buffer. Equitywise Property Group can help you connect strategy, research, acquisition and ongoing portfolio support before a costly decision is made.

“I had no idea where to start with property investing, but after working with this team, I now have a solid investment strategy and a growing portfolio. I couldn’t be happier with the results!”
John D., Melbourne
“I had no idea where to start with property investing, but after working with this team, I now have a solid investment strategy and a growing portfolio. I couldn’t be happier with the results!”
John D., Melbourne
“I had no idea where to start with property investing, but after working with this team, I now have a solid investment strategy and a growing portfolio. I couldn’t be happier with the results!”
John D., Melbourne
“I had no idea where to start with property investing, but after working with this team, I now have a solid investment strategy and a growing portfolio. I couldn’t be happier with the results!”
John D., Melbourne
“I had no idea where to start with property investing, but after working with this team, I now have a solid investment strategy and a growing portfolio. I couldn’t be happier with the results!”
John D., Melbourne